0.1 Determinants
Finally determinants! One of the most foundational concepts in linear algebra is the determinant. Being one of the foundational concepts, I also think it is a hard concept if the intuition is excluded in the discussion due to its formula heavy nature.
As you could have noticed, a linear transformation does not only change the position of the vectors. Consider the following diagram.
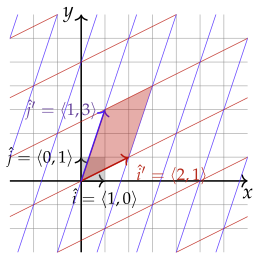
Notice that from the diagram above, the gray area is scaled to the new red area. Notice that the area of the new parallelogram is \(3 \cdot 4 - 1 \cdot 2 \cdot \frac {1}{2} \cdot 2 - 1 \cdot 3 \cdot \frac {1}{2} \cdot 2 - 1 \cdot 2 = 12 - 2 - 3 - 2 = 5\). Because the area which was originally \(1\) is scaled to \(5\), we can say that \[ \begin {vmatrix} 2 & 1 \\ 1 & 3 \end {vmatrix} = 5 \] holds. The determinant is only defined for square matrices, and for each square matrix, the determinants tell how much the area has changed after the linear transformation. Determinants can surely be negative, and they represent the change in orientation. With this intuition in mind, let’s discuss more computational perspective of determinants.
Before we discuss the formula for determinants, let’s define a notation.
Definition 0.1.1
The minor of matrix \(A\), denoted as \(M_{ij}\), is a submatrix of \(A\) without the \(i^\text {th}\) row and \(j^\text {th}\) column of \(A\). The cofactor of \(a_{ij}\) is defined as \((-1)^{i+j} \det (M_{ij})\).
Consider the following examples for \(A\) defined as the following. \[ A = \begin {bmatrix} a_{11} & a_{12} & a_{13} & a_{14} \\ a_{21} & a_{22} & a_{23} & a_{24} \\ a_{31} & a_{32} & a_{33} & a_{34} \\ a_{41} & a_{42} & a_{43} & a_{44} \end {bmatrix} \] \(M_{11}\) and \(M_{24}\) are defined as the following. \[ M_{11} = \begin {bmatrix} a_{22} & a_{23} & a_{24} \\ a_{32} & a_{33} & a_{34} \\ a_{42} & a_{43} & a_{44} \end {bmatrix}, \quad M_{24} = \begin {bmatrix} a_{11} & a_{12} & a_{13} \\ a_{31} & a_{32} & a_{33} \\ a_{41} & a_{42} & a_{43} \end {bmatrix} \] Now let’s define what determinants are with a recursive formula.
Definition 0.1.2
The determinant of a square matrix \(A\), denoted as \(\det (A)\) or \(|A|\), is a value defined with the following rules.
- 1.
- \(\det (A) = a_{11}\) if \(A = [a_{11}]\).
- 2.
- The following equation can be used to determine \(\det (A)\) for \(A\) with order \(n \times n\) for \(n > 1\). \[ \det (A) = \sum _{j=1}^n (-1)^{1 + j} a_{1j} \det (M_{1j}) \]
Let’s take a look at an example with a \(2 \times 2\) matrix \(A = [a_{ij}]\). \begin{align*} \det (A) &= \sum _{j=1}^2 (-1)^{1 + j} a_{1j} \det (M_{1j}) \\ &= (-1)^{1 + 1} a_{11} \det (M_{11}) + (-1)^{1 + 2} a_{12} \det (M_{12}) \\ &= (-1)^{2} a_{11} a_{22} + (-1)^{3} a_{12} a_{21} \\ &= a_{11} a_{22} - a_{12} a_{21} \end{align*}
Returning to our first example, we can verify that the formula holds. \[ \begin {vmatrix} 2 & 1 \\ 1 & 3 \end {vmatrix} = 2 \cdot 3 - 1 \cdot 1 = 5 \] We could also derive the formula for higher orders with many computations but I will leave them for you! I also think it is just better to use the recursive formula and the formula for \(2 \times 2\) matrices instead of memorizing complex formulas, but I don’t know. I think it’s up to you. Below is another example.
With these in mind, we can establish a very important theorem in computing determinants.
Theorem 0.1.3
For any square matrix \(A\), the cofactor expansion along the \(i^\text {th}\) row and the cofactor expansion along the \(j^\text {th}\) column equal. In other words, the following equation holds. \[ \det (A) = \sum _{j=1}^n (-1)^{i + j} a_{ij} \det (M_{ij}) = \sum _{i=1}^n (-1)^{i + j} a_{ij} \det (M_{ij}) \]
Let’s save the proof for the theorem for later as we need to show different properties of determinants before proving the theorem above. For now, let’s discuss a special property of triangular matrices.
Theorem 0.1.4
For a triangular (upper or lower) matrix \(A_{n \times n} = [a_{ij}]\), the determinant is defined as the following. \[ \det (A) = \prod _{i=1}^n a_{ii} \]
Proof.
First, the case for upper triangular matrix can be proven. Notice that \(\det (A) = \sum _{i=1}^n (-1)^{i + 1} a_{i1} \det (M_{i1}) = a_{11} \det (M_{11})\) by Theorem 0.1.3. Continuing, notice that \(M_{11}\) is another upper triangular matrix by definition.
If such calculations are continued, it is evident that the last term would be \(a_{nn}\). Similarly, the second to the last term would be \(a_{nn} a_{n-1,n-1}\). By inductive hypothesis, it is evident that \[ \det (A) = a_{11} \det (M_{11}) = a_{11} \prod _{i=2}^n a_{ii} = \prod _{i=1}^n a_{ii} \] and the theorem holds for upper triangular matrix.
The case for lower triangular matrix can be proven in similar manner. Note that \(\det (A) = \sum _{j=1}^n (-1)^{1 + j} a_{1j} \det (M_{1j}) = a_{11} \det (M_{11})\). With the same inductive hypothesis above, it can be concluded that \[ \det (A) = a_{11} \det (M_{11}) = a_{11} \prod _{i=2}^n a_{ii} = \prod _{i=1}^n a_{ii} \] and the theorem holds.
As you could have guessed, we get a direct corollary from the theorem.
Proof.
First and foremost, notice that a diagonal matrix is both an upper and lower triangular matrix. Thus by Theorem 0.1.4, the corollary holds.
Continuing from triangular matrices, we can also apply our understanding of a transpose of a matrix. Consider the following theorem.
Proof.
First and foremost, notice that \(A = A^\intercal \) if \(A\) is a \(1 \times 1\) matrix. Thus, the theorem holds for any \(A_{1 \times 1}\). Continuing, note that for \(A_{n \times n}\) with \(n > 1\), \(M_{ij}\) equals \(M'_{ij}\) for \(A^T\). Moreover by definition, \(M'_{ij} = M_{ji}\) and the following equation holds \(A^\intercal = [a'_{ij}]\). \begin{align*} \det (A) &= \sum _{i=1}^n (-1)^{i + 1} a_{i1} \det (M_{i1}) \\ &= \sum _{j=1}^n (-1)^{1 + j} a'_{1j} \det (M'_{1j}) \\ &= \det \left ( A^\intercal \right ) \end{align*}
Thus, the theorem holds.
Now that we discussed the relationships between matrices and determinants, let’s conclude our discussion with products and determinants.
0.1.1 Determinant and Products
Before we conclude our discussion on determinant and this note, I wished to introduce one of the most important results of determinants. In this part of the section, we will try to prove that the product of the determinants is the same as the determinant of the product. To prove this result, we would need a lot of lemmas, so let’s get started with the first one.
Lemma 0.1.7
For a matrix \(A_{n \times n}\) and an elementary matrix \(E_{n \times n}\) for interchanging two rows, \(\det (E) = -1\) and \(\det (EA) = \det (E) \det (A)\).
Proof.
First and foremost, the case when \(E\) exchanges two consecutive rows can be proven. Let \(B = FA\) where \(F\) is the \(n \times n\) elementary matrix that interchanges the \(k^\text {th}\) and \(k+1^\text {th}\) rows of \(A\). Therefore, for \(A = [a_{ij}]\) and \(B = [b_{ij}]\), \(b_{k+1,j} = a_{kj}\) holds and for the minor of \(B\) as \(M'_{ij}\), \(M'_{i+1,j} = M_{ij}\). Moreover, notice that \(F = -1\) for \(n = 2\) and by inductive hypothesis with exchanging the use of \(\det (A) = (-1)^2 a_{11} \det (M_{11})\) and \(\det (A) = (-1)^{2n} a_{nn} \det (M_{nn})\), it is evident that \(\det (F) = -1\). Thus, the following equations hold. \begin{align*} \det (B) &= \sum _{j=1}^n (-1)^{k+1+j} b_{k+1,j} \det (M'_{k+1,j}) \\ &= \sum _{j=1}^n (-1)^{k+1+j} a_{kj} \det (M_{kj}) \\ &= -\sum _{j=1}^n (-1)^{k+j} a_{kj} \det (M_{kj}) \\ &= -\det (A) \end{align*}
Thus, \(\det (FA) = \det (F) \cdot \det (A)\). Continuing, notice that any exchange between two consecutive rows requires one \(F\). Moreover, any exchange between two rows with a row in between requires three \(F\)s. Since any exchange can be performed with the combination of such two operations, it is evident that every \(E\) can be represented as odd number of \(F\)s. Therefore, the following equations hold for odd \(m\). \begin{align*} \det (EA) &= \det (F_1 F_2 \cdots F_m A) = \det (F_1) \det (F_2) \cdots \det (F_m) \det (A) \\ &= (-1)^m \det (A) = -\det (A) \\ &= \det (E) \det (A) \end{align*}
Thus, the lemma holds.
Continuing from this lemma, we can establish an interesting corollary.
Corollary 0.1.8
The equation \(\det (A) = 0\) holds for all square matrices \(A\) with either two identical rows or columns.
Proof.
Let \(k_1\) and \(k_2\) be the identical rows of the matrix \(A\). For an elementary matrix \(E\) that interchanges the rows \(k_1\) and \(k_2\), the following equations hold by Lemma 0.1.7. \[ \det (A) = \det (EA) = \det (E) \det (A) = -\det (A) \] Thus, \(\det (A) = 0\). Similarly, if \(A\) has two identical columns \(k_1\) and \(k_2\), the same argument applies by Theorem 0.1.6 as \(\det (A) = \det (A^\intercal )\).
For our second lemma, we have another elementary row operation.
Lemma 0.1.9
For a matrix \(A_{n \times n}\) and an elementary matrix \(E_{n \times n}\) that scales \(k^\text {th}\) row of \(A\) by some nonzero scalar \(\lambda \), \(\det (E) = \lambda \) and \(\det (EA) = \det (E) \det (A)\).
Proof.
First and foremost, because \(E_{n \times n} = k\), it is evident that utilizing \(\det (A) = (-1)^2 a_{11} \det (M_{11})\) and \(\det (A) = (-1)^{2n} a_{nn} \det (M_{nn})\), appropriately will lead to \(\det (E) = \lambda \) with inductive hypothesis. Moreover, consider the following equations. \begin{align*} \det (EA) &= \sum _{i=1}^n (-1)^{1+k} \lambda a_{ik} \det (M_{ik}) \\ &= \lambda \sum _{i=1}^n (-1)^{1+k} a_{ik} \det (M_{ik}) \\ &= \lambda \det (A) = \det (E) \det (A) \end{align*}
Thus, the lemma holds.
Just like our first lemma, we can expand this second lemma with an interesting corollary.
Corollary 0.1.10
For any matrix \(A_{n \times n}\) and scalars \(\lambda \), \(\det (\lambda A) = \lambda ^n \det (A)\).
Proof.
Let \(E_k\) be the elementary row operation that scales the \(k^\text {th}\) row of \(A\) by \(\lambda \). Then, the following equations hold by Lemma 0.1.9. \begin{align*} \det (\lambda A) &= \det ( E_n E_{n-1} \cdots E_1 A) \\ &= \det (E_n) \det (E_{n-1}) \cdots \det (E_1) \det (A) \\ &= \lambda ^n \det (A) \end{align*}
Thus, the corollary holds.
Below is the third lemma on determinants and elementary matrices.
Lemma 0.1.11
For a matrix \(A_{n \times n}\) and an elementary matrix \(E\) of the same order that adds \(\lambda \) times row \(k_1\) to row \(k_2\) of \(A\), then \(\det (E) = 1\) and \(\det (EA) = \det (E) \det (A)\).
Proof.
First and foremost, notice that \(E\) is a triangular matrix and the elements in its diagonal are all \(1\). Thus by Theorem 0.1.4, \(\det (E) = 1\).
Consider a new matrix \(B\) that is obtained by replacing \(k_2\) with \(k_1\) from \(A\). Then, \(b_{k_2j} = a_{k_1j}\) and the minor \(M'_{ij}\) of \(B\) satisfy \(M'_{k_2j} = M_{k_2j}\). Moreover by Corollary 0.1.8, \(\det (B) = 0\). Therefore, the following equations hold. \begin{align*} &\quad \ \det (EA) \\ &= \sum _{j=1}^n (-1)^{k_2 + j} (a_{k_2j} + \lambda a_{k_1j}) \det (M_{k_2j}) \\ &= \sum _{j=1}^n (-1)^{k_2 + j} (a_{k_2j}) \det (M_{k_2j}) + \lambda \sum _{j=1}^n (-1)^{k_2 + j} (a_{k_1j}) \det (M_{k_2j}) \\ &= \det (A) + \lambda \det (B) = \det (A) \end{align*}
Thus \(\det (EA) = \det (A) = \det (E) \det (A)\).
With the three lemmas above, we can establish an important theorem that links the determinants of a matrix and an elementary matrix.
Theorem 0.1.12
For a matrix \(A_{n \times n}\) and any elementary matrix \(E\) of the same order, \(\det (EA) = \det (E) \det (A)\).
Proof.
By definition, there exists three different elementary matrices that interchanges rows, scales a row, or add a scaled row to the other. By Lemmas 0.1.7, 0.1.9, and 0.1.11, \(\det (EA) = \det (E) \det (A)\) for all elementary matrices \(E\).
Now, I know it’s lots of statements, but I promise we will get to the main result. Let’s take a look at one last important result to get to our desired theorem! This theorem and its result include the topic of invertibility, which has not been introduced yet. Please feel free to read Section 3.3 and return or vice versa as it shouldn’t be something too hard.
Proof.
First, notice that \(A\) is invertible if and only if there exists a sequence of elementary matrices \(E_1, \ldots , E_k\) such that \(E_k \cdots E_1 A = U\) holds for some upper triangular matrix \(A\). In other words, \[ \det (E_k) \cdots \det (E_1) \det (A) = \det (U) \] where \(\det (E_i) \neq 0\) and \(\det (U) \neq 0\). Moreover, there exists such elementary matrices if and only if \(\det (A) \neq 0\). Thus, the theorem holds.
Now finally! Let’s prove the theorem!
Theorem 0.1.14
For square matrices \(A\) and \(B\) with the same order, \(\det (AB) = \det (A) \det (B)\).
Proof.
First, the theorem can be shown for the case where \(A\) is not invertible. Notice that if \(A\) is not invertible, then \(AB\) must also be not invertible as if \(AB\) is invertible, then there exists a matrix \(C\) such that \((AB)C = I\) and \(A(BC) = I\), which is contradictory. Thus by Theorem 0.1.13, \(\det (AB) = 0 = 0 \cdot \det (B) = \det (A) \det (B)\) and the theorem holds for not invertible \(A\).
Continuing, the case for invertible \(A\) can be proven. By definition, if \(A\) is invertible, then it can be represented as a product of sequence of elementary matrices \(E_1, \ldots , E_k\). Therefore, \(\det (AB) = \det (E_1 \cdots E_k B) = \det (E_1 \cdots E_k) \det (B) = \det (A) \det (B)\) by Theorem 0.1.12. Thus, the theorem holds.
With this important theorem in mind, let’s wrap up our notes with two corollaries.
Proof.
Notice that \(1 = \det (AA^{-1}) = \det (A) \det (A^{-1})\) by Theorem 0.1.14. Therefore, \(\det (A^{-1}) = \frac {1}{\det (A)}\).
Continuing, below is the second corollary.
Proof.
By definition, if \(A\) and \(B\) are similar, then there exists an invertible matrix \(P\) that satisfy \(A = P^{-1} B P\). Therefore by Theorem 0.1.14 and Corollary 0.1.15, \(\det (A) = \det (P^{-1}) \det (B) \det (P) = \frac {1}{\det (P)} \cdot \det (B) \det (P) = \det (B)\) and the corollary holds.
This is it for determinants! I think it is an interesting way to connect the relationship between linear transformations, which we will discuss in future notes and matrix representation of their effects. In the next notes, we will discuss different applications of matrices.